Proposal would address outstanding obligations, provide critical funding for essential services and establish long-term financial accountability measures
U.S. VIRGIN ISLANDS — Governor Albert Bryan Jr. announced Monday that his administration will submit a proposed $250 million bond-financing package to the 36th Legislature aimed at addressing longstanding financial obligations, strengthening the Territory’s hospitals and public utilities, and meeting outstanding commitments to residents and government vendors.
The proposal, developed by the Financial Solutions Task Force established by Governor Bryan in July, would direct $85 million to the Territory’s two hospitals, provide $80 million in combined financial assistance to the Virgin Islands Water and Power Authority (WAPA) and Virgin Islands Waste Management Authority (VIWMA), and allocate additional funding toward retroactive wage payments, tax refunds and other outstanding obligations.
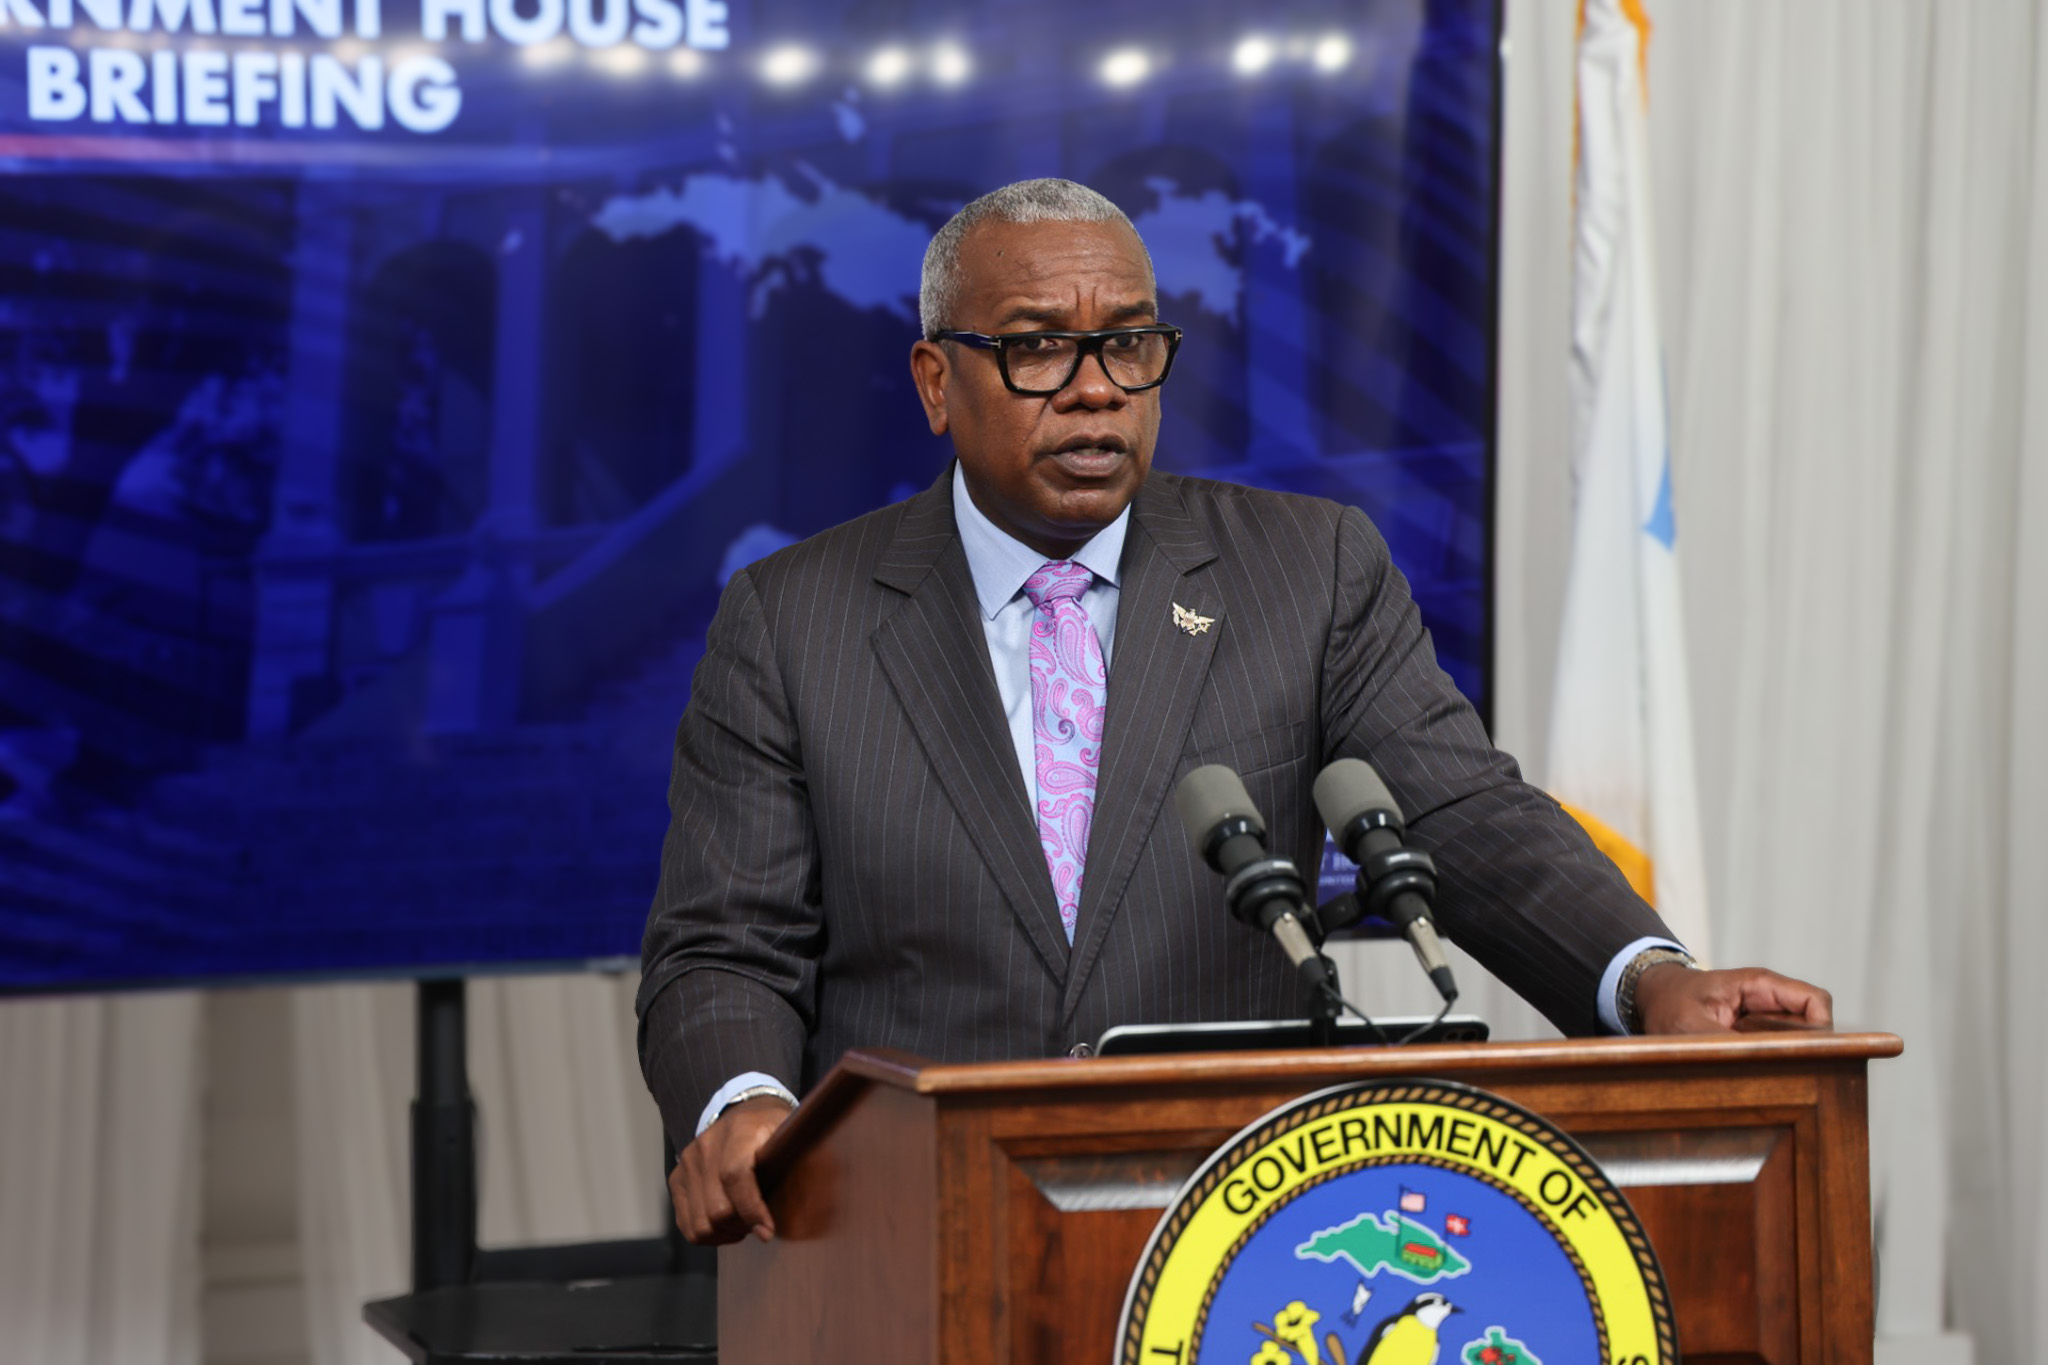
Speaking during Monday’s Government House press briefing, Governor Bryan said the proposal represents an opportunity to address existing financial pressures while establishing stronger safeguards to help participating institutions improve their financial performance and reduce their reliance on Central Government support.
“These are obligations and financial pressures that already exist, and continuing to carry them without a comprehensive solution has a cost of its own,” Governor Bryan said. “Our goal isn’t just to meet the immediate financial need. It’s to make an investment today that puts these institutions in a stronger position tomorrow, with the resources and accountability they need to serve our people effectively.”
Under the proposed financing package, Schneider Regional Medical Center would receive $45 million, while the Governor Juan F. Luis Hospital and Medical Center would receive $40 million to help address pressing financial needs, including outstanding vendor obligations and the costs associated with maintaining essential healthcare services.
Governor Bryan acknowledged the financial pressures facing both hospitals, including difficulties maintaining adequate supplies and meeting obligations to vendors, while emphasizing the importance of strengthening hospital operations alongside the Territory’s ongoing investments in rebuilding and modernizing healthcare facilities.
“As we make historic investments in rebuilding our healthcare infrastructure, we also have to make sure the institutions operating those facilities have the financial resources necessary to serve our people,” the Governor said.
The proposal would also allocate $40 million each to WAPA and VIWMA to help address outstanding financial obligations and support the continued delivery of electricity, water and waste management services.
Additional proposed allocations include:
- $30 million for retroactive wage payments and tax refunds owed to Virgin Islanders.
- $10 million to address outstanding government vendor payments.
- $30 million toward repayment of an existing government line of credit.
The package would also provide funding for capital needs within the Legislative and Judicial branches and economic development initiatives through the Virgin Islands Economic Development Authority.
A central feature of the proposal is a series of financial accountability measures intended to ensure that the financing provides more than temporary relief.
Participating institutions would be required to develop five-year financial sustainability plans, strengthen financial reporting and audit compliance, and establish measurable goals for improving operational efficiency and reducing their dependence on Central Government assistance over time.
The proposal also calls for regular progress reviews and corrective action when necessary to help institutions meet their financial and operational objectives.
Governor Bryan said these safeguards are essential to ensuring that the financing supports lasting improvements rather than allowing existing financial pressures to continue unchecked.
The proposed bonds would be backed by Gross Receipts Tax revenues and subject to defined limits on interest rates and repayment terms. The financing would require legislative approval before moving forward.
The eight-member Financial Solutions Task Force brings together senior administration officials and members of the 36th Legislature. Its leadership includes Office of Management and Budget Director Julio Rhymer and Sen. Novelle E. Francis Jr., chairman of the Legislature’s Committee on Budget, Appropriations and Finance.
Other legislative members are Sens. Marvin Blyden and Avery Lewis. The administration’s representatives also include Department of Finance Commissioner Kevin McCurdy, Virgin Islands Public Finance Authority Executive Director Nathan Simmonds and Division of Personnel Director Cindy Richardson.
Governor Bryan thanked the task force members for their collaborative work in developing the proposal, noting that addressing the Territory’s longstanding financial challenges requires cooperation between the executive and legislative branches.
The Governor said he intends to transmit the necessary legislation to the 36th Legislature in the coming days and looks forward to working with lawmakers to advance the proposal.
“As we approach the final months of our administration, we are continuing to look for opportunities to strengthen the financial foundation of our government and the institutions that serve our community,” Governor Bryan said. “These are complex challenges, but they are challenges we have a responsibility to address. I believe this proposal gives us an opportunity to do that in a responsible and meaningful way.”
###
Comments are closed